Commercial Flood Insurance
Coverage Snapshot: Commercial property policies normally exclude flood. The NFIP caps non-residential coverage at $500,000 building and $250,000 contents per building, and does not provide business interruption. Private commercial flood markets can write above those caps and may add replacement cost, loss of rents, and business interruption. Portfolios with several buildings can often be consolidated onto a single scheduled policy.
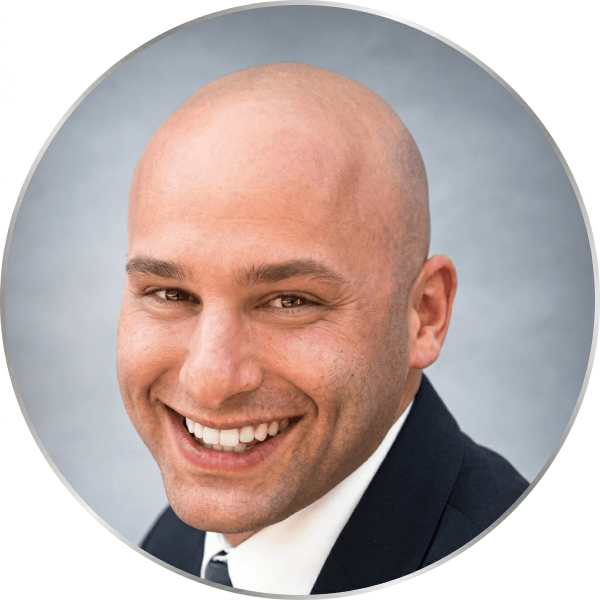
Your WHINS Advisor
Request a quote from Darren Hasson
Agency Principal / Insurance Advisor
Darren works with California commercial accounts that need practical guidance through difficult underwriting, specialty markets, and contract-driven insurance requirements.
Call: 818-233-0825 ext. 101 | Direct: 818.233.0838 | Email: [email protected]
License #0F22646 | NPN #8821764
How WHINS helps
A practical review process for this risk
- Confirm each location’s address, flood zone, occupancy, construction, square footage, and total insured value.
- Compare an NFIP placement against private commercial primary options, and price an excess layer above the NFIP where that combination prices better.
- Review whether business interruption, loss of rents, and replacement cost on buildings can be added for the risk.
- For multi-building portfolios, evaluate a scheduled policy so every location sits under one renewal with its own modeled limit.
Common Situations We See
Where this coverage conversation usually starts
A lender or a lease requires flood coverage on a commercial building, a property is remapped into a higher-risk zone, or an owner realizes the NFIP $500,000 cap is a fraction of the building’s replacement cost. Owners with several buildings often carry a stack of separate NFIP policies with different renewal dates and no business interruption anywhere in the program.
Downloads
Commercial flood quote checklist and application
These downloads are starting points only. We may request different or additional applications depending on carrier appetite, state, class, and underwriting details.
What should a property owner review first?
- Flood is typically excluded from commercial property and commercial package policies.
- NFIP non-residential limits are capped at $500,000 building and $250,000 contents per building.
- The NFIP commercial form does not provide business interruption or loss of rents.
- Private commercial flood can be written above the NFIP caps and may add replacement cost on buildings, loss of rents, and business interruption.
- Commercial underwriters are often willing to write an excess layer above an NFIP policy, so primary plus excess is a common structure on this side of the market.
What do underwriters usually need?
Expect to provide the full location schedule with addresses, flood zone for each location, construction type, year built, number of stories, square footage, occupancy, total insured value split between building and contents, prior flood losses, and any elevation or flood mitigation details. Lender and lease requirements should be provided up front because they often drive the required limit.
When does a scheduled flood policy make sense?
When an owner has multiple buildings, whether on one parcel or spread across addresses. Each building is listed individually with its own coverage amount and modeled by geocoded coordinates, which consolidates several separate policies and renewal dates into one program.
What common mistakes should be avoided?
The frequent ones are insuring to the NFIP cap and assuming that is adequate, leaving business interruption out of the program entirely, letting several single-building policies renew on different dates, understating total insured value, and discovering a waiting period after a contract or loan has already been scheduled to close.
What documents make the quote process faster?
Useful documents usually include the location schedule, current flood policies or declarations pages, statement of values, loss runs, lender or lease insurance requirements, elevation certificates where they exist, and recent building updates or flood mitigation work.
How do I start?
Start with a quote request and include your current flood policy or declarations page, any elevation information you already have, the property address, and your desired limits. WHINS Insurance Agency can review the request and route it to the right licensed team member.
- Phone: 818-233-0825
- Email: [email protected]
- California license: 0G66655
Common questions
Does a commercial property policy cover flood?
Usually not. Flood is typically excluded from commercial property forms and needs a separate flood policy or a difference in conditions placement.
What are the NFIP limits for a commercial building?
The NFIP caps non-residential building coverage at $500,000 and contents at $250,000 per building. Private commercial flood markets can be written above those caps.
Can business interruption be covered for a flood?
Business interruption and loss of rents are generally not available under the NFIP commercial form, but they can sometimes be added through private flood markets. Availability depends on the risk and underwriting.
How does a scheduled flood policy work?
A scheduled policy covers multiple buildings under one policy, with each building listed separately and assigned its own coverage amount. Locations are modeled individually by geocoded coordinates, whether they sit on one parcel or at separate addresses.
Related WHINS resources
- Residential Flood Insurance, if the property is a home rather than a commercial building.
- Urban Surplus Landlord Portfolio Insurance
- CA Earthquake Commercial Property Insurance
- Personal Parametric Insurance, which covers trigger-based payouts for events including flood and complements rather than replaces a flood policy.
References and useful official resources
- FloodSmart, the official NFIP consumer site from FEMA
- California Department of Insurance flood insurance guide
This page is for educational and marketing purposes only. It is not legal, tax, HR, medical, regulatory, underwriting, or coverage advice. Coverage availability, terms, limits, pricing, and eligibility depend on underwriting review, carrier appetite, applicable law, and actual policy language.
Ready to start?
Send us the basic details and WHINS will help review the next underwriting step for this risk.